Skip to content
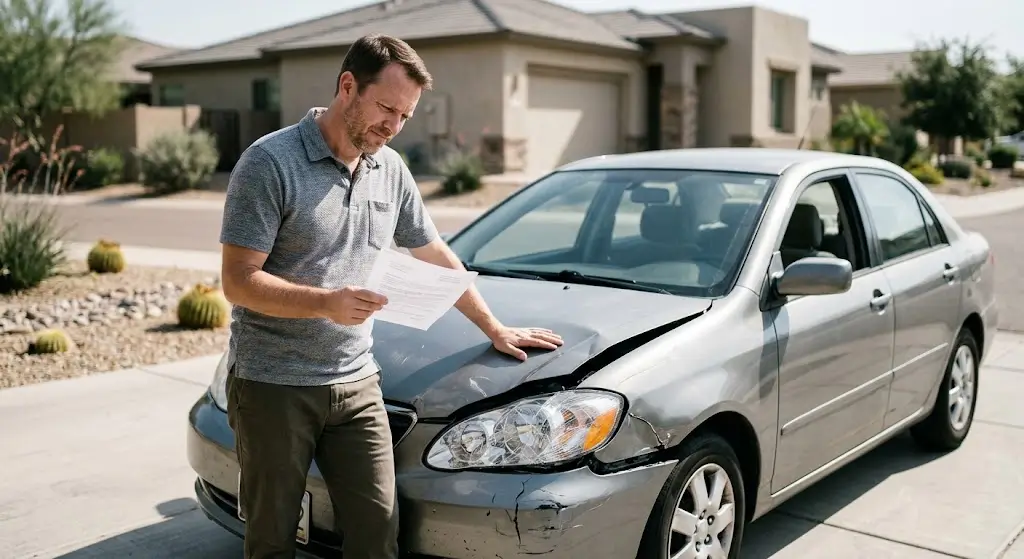
Most people assume the vehicle portion of a crash claim is straightforward. In reality, it rarely is. The reason comes down to how Arizona regulates total loss calculations governed by a specific rule that few claimants ever read, and that insurance adjusters certainly don’t volunteer. The offer sitting in front of you was generated within a rigid legal framework, and key elements of that framework are routinely ignored or overlooked.
When Is a Vehicle a Total Loss in Arizona?
A vehicle is considered a total loss when its total repair cost plus its salvage value meets or exceeds its actual cash value (ACV). Because Arizona uses this total loss formula instead of a fixed percentage cutoff, there is no “70% rule” to rely on. A newer car with a high pre-crash value can suffer substantial damage and still be deemed repairable, whereas an older car with modest value can easily be written off after minor panel damage.
This dynamic creates two distinct realities. First, the insurer’s final decision hinges heavily on its own internal estimates for both repair costs and ACVwhich means an artificially low valuation makes a total loss far more likely. Second, once a vehicle is declared a total loss and processed for salvage, its title is permanently branded, forever lowering what the car could ever sell for in the future.
How Must an Insurer Calculate Your Total Loss Payout?
Insurers must follow a closed list of approved methods. Arizona Administrative Code R20-6-801, adopted under the Unfair Claim Settlement Practices statute (A.R.S. § 20-461), establishes the precise standards for first-party auto total loss claims. Under Subsection (H)(1), an insurance company is permitted to:
- Offer a specific, comparable replacement vehicle that is currently available in the local market, covering all applicable taxes, license fees, and transfer fees at no extra cost to you beyond your policy deductible (with the offer and any rejection formally documented in the claim file); or
- Pay out a cash settlement based on the actual market cost to buy a comparable vehicle, including all applicable taxes, licensing fees, and transfer costs.
If no comparable vehicle can be found in your local market area, the rule directs the insurer to gather two or more written quotations from qualified local dealers.
Here is why that matters in real life: an arbitrary number pulled from an internal valuation software report without identified local comparables or dealer quotes attached does not satisfy any of the settlement methods outlined in the regulation.
What Must Be Included That Insurers Often Leave Out?
Taxes and government fees are mandatory components of the settlement. The regulation explicitly requires insurers to include all applicable taxes, licensing fees, and other transfer costs required to put a replacement car on the road. Official guidance from the Arizona Department of Insurance confirms that this includes state, county, and municipal sales taxes, air quality fees, and registration costs.
If your settlement offer looks like a bare-bones valuation without any room for the actual costs of buying and registering a replacement vehicle, you should challenge that figure in writing before signing anything.
Are Those Deductions Even Allowed?
Deductions are only legal if they are properly itemized and justified. This provision is often a claimant’s strongest tool. When an offer strays from standard valuation methods, R20-6-801 mandates that any deviation be backed up by clear documentation of the vehicle’s true condition. Any deductions including those for salvage value must be measurable, discernible, fully itemized, and appropriate in dollar amount. Furthermore, the exact basis for the settlement must be clearly explained to you.
A generic line item on a report reading “condition adjustment: −$1,200,” with no explanation or supporting breakdown, falls short of this legal requirement. The same goes for unexplained deductions for mileage or pre-existing damage. Simply asking the adjuster to provide the line-by-line itemization required by law is often enough to shift the settlement number in your favor.
Additionally, a key protection exists for third-party claimants: when liability and damages are reasonably clear, insurance companies are legally prohibited from advising a third party to file through their own policy instead.
What If the Car Is Repairable Instead?
Different rules apply when a car can be repaired, but the governing standard remains the same. For repairable vehicles, R20-6-801 requires an estimate that can reasonably be expected to restore the car to its pre-collision condition. Three key rules stem from this:
- Hidden damage must be paid for. If mechanics discover additional damage once tear-down begins, the insurer is required to adjust the repair estimate rather than cap payment at the initial quote.
- Sales tax applies to repairs. Taxes on both replacement parts and shop materials must be factored into the payout.
- Designated shops must deliver full restoration. If the insurer directs you to a specific body shop, they are obligated to restore the vehicle to pre-loss condition at no extra cost to you beyond your agreed deductible, within a reasonable timeframe.
Outside of a total loss scenario, the rule also prevents insurers from basing a first-party cash settlement on an amount lower than what actual repairs would cost, unless you explicitly agree to it. Most disputes in this area center on aftermarket parts, “betterment” deductions, or paint blend timesall of which can be challenged using the pre-collision condition standard.
The Gap Nobody Mentions: Diminished Value
Even when a damaged car is impeccably repaired, it loses market value. Arizona appellate court precedents establish that compensation for a negligently damaged vehicle can include both the repair bill and the proven residual diminution in fair market value, along with loss of use during the shop timeline. Given two identical cars, any buyer will pay less for the one showing an accident on its vehicle history report. That lost resale value represents a separate, recoverable economic harm.
However, there is an important limit to keep in mind: in Arizona, a diminished value claim must be brought against the at-fault driver’s liability insurance. You generally cannot recover diminished value through your own collision coverage or uninsured motorist policy. If the driver who hit you was uninsured or fled the scene, you may not have a pathway to recover diminished value even if your personal injury claim moves forward.
Pursuing lost market value alongside vehicle repairs is a nuanced process that an auto accident attorney Phoenix residents trust can guide you through effectively.
Insurers frequently try to cap these claims using a formula known as “17c,” which limits the base loss to 10 percent before applying downward multipliers. Arizona courts have never adopted this formula. Under state case law, all that is required is proof of actual loss which is best established through an independent appraisal based on real local market comparables rather than an insurer’s internal algorithm.
How Do You Dispute a Valuation?
If you receive an inadequate offer, you have four main avenues for pushing back, generally escalated in this order:
- Demand full itemization. Request the specific local comparables, dealer quotes, and detailed line-item deductions required by R20-6-801.
- Submit your own comparables. Pull local market listings for vehicles matching your car’s exact year, trim level, mileage, and option packages. Real local listings hold significant weight, particularly if the adjuster used out-of-area comparables.
- Invoke the appraisal clause. Check your insurance policy for an appraisal clause, which creates a formal path to resolve valuation disputes through independent appraisers.
- File a state complaint. Submit a formal complaint with the Arizona Department of Insurance and Financial Institutions, which oversees insurer compliance with state settlement rules.
Crucially, do not cash any check marked “final settlement” or “payment in full” while your property claim remains unresolved, as doing so can be used against you to terminate the claim. Rejecting an unfair initial offer costs you nothing but time, and a stubborn refusal from the adjuster simply shifts the claim into disputed territory.
Deadlines and Fault
Property damage claims in Arizona carry the exact same two-year statute of limitations as personal injury actions. Under A.R.S. § 12-542, the clock starts running on the date of the collision, meaning you do not get extra time to resolve a vehicle dispute compared to an injury claim.
Comparative fault rules also apply directly to property damage. Arizona operates under a pure comparative negligence system pursuant to A.R.S. § 12-2505. Any percentage of fault assigned to you will reduce your vehicle recovery by that exact percentage, though you are not barred from recovering even if you share a majority of the blame.
Frequently Asked Questions
When does Arizona consider a car a total loss? When the total cost of repairs plus the vehicle’s salvage value equals or exceeds its actual cash value. Because Arizona uses this specific formula rather than a flat percentage threshold, the outcome hinges on the insurer’s valuation of both repair costs and ACVmeaning an undervalued vehicle is far more likely to be declared a total loss.
Does my insurer have to pay sales tax and registration fees on a total loss? Yes. Under Arizona Administrative Code R20-6-801, a total loss settlement must incorporate all applicable sales taxes, licensing fees, and transfer costs. Official guidance from the Department of Insurance explicitly confirms that these transaction costs must be included.
Can the insurance company deduct for the condition of my car? Only if they provide proper itemization and proof. R20-6-801 mandates that any settlement deductionincluding salvage adjustmentsmust be measurable, discernible, fully itemized, and reasonable in amount, with a clear explanation provided to you. A vague “condition adjustment” line item does not fulfill this standard.
What if more damage is found after repairs start? The rule states that the initial repair estimate must reflect the full cost needed to restore the vehicle to its pre-collision state. If mechanics uncover hidden damage after work begins, the insurer is required to issue a supplemental adjustment rather than capping payment at the original quote.
Can I claim diminished value in Arizona? Yes, but you must pursue it through the at-fault driver’s liability carrier. Arizona law allows vehicle owners to recover repair costs alongside proven residual loss in fair market value and loss of use. You generally cannot collect diminished value through your own collision or uninsured motorist coverage.
How do I dispute a total loss valuation? Start by requesting the local comparables and itemized deduction breakdown required by state regulations. Next, gather your own local sales listings, leverage your policy’s appraisal clause if available, and consider filing a formal complaint with the Arizona Department of Insurance and Financial Institutions. Above all, do not cash any settlement checks marked as full payment while negotiations are open.
Before You Accept the Vehicle Offer
Remember that an adjuster’s total loss payout figure is generated through a regulatory framework that places real constraints on the insurer. Asking which calculation method was applied, requesting the underlying comparables, and demanding a breakdown of every deduction is not being argumentative; it is simply holding the carrier to the documentation standards Arizona law already demands.
Harris Injury Law, PLLC 1136 E Campbell Ave, Phoenix, AZ 85014 (480) 800-4878
Consultations are free and injury cases run on a contingency fee, meaning no attorney fee unless compensation is recovered. Request a consultation or meet our attorneys. Every case depends on its own facts; no outcome can be promised or predicted.
This article provides general information about Arizona law and is not legal advice. Reading it creates no attorney-client relationship. Arizona statutes and insurance regulations change, and outcomes depend on the specific facts and policy involved. Consult a licensed Arizona attorney about your situation.
Reviewed by Jason A. Harris, Harris Injury Law, PLLC.