Skip to content
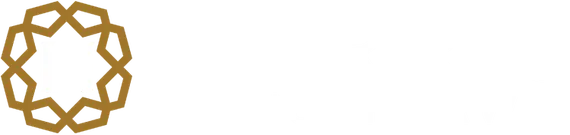
An offer arriving within days of a crash feels like the system is working. It is usually the opposite. The adjuster who called you knows things you do not yet know how long injuries like yours typically take to resolve, what the treatment usually costs, and what a claim like this settles for once it has been documented. You are being asked to decide with the least information you will ever have.
That does not make every early offer unfair. Some are reasonable. The point is to know which one you have before the decision becomes permanent.
Why Does the Offer Arrive So Fast?
Because the insurer’s exposure only grows from here. In the first two weeks you have a police report, maybe an emergency room visit, and no idea whether the neck pain resolves in a month or becomes a surgical problem. The carrier is pricing that uncertainty in its favor.
Speed also buys something else: it reaches you before you have spoken to anyone who values claims for a living, and often before your own doctor has finished investigating. Symptoms that surface late are common and legitimate, which is exactly why an injury that shows up a week later is so costly to have already settled.
What Does Signing a Release Actually Do?
It ends the claim permanently, whatever happens next. A settlement release is a contract. Once signed and the check is cashed, you generally cannot reopen the claim if you need injections in six months or surgery in a year. There is no reconsideration clause.
Two related traps are worth naming:
A release can be broader than the payment. General release language may extinguish claims against parties beyond the one writing the check including drivers or companies whose involvement has not been identified yet.
A property damage check can carry release language. Cashing a check endorsed “final settlement” or “payment in full” is sometimes argued to close more than the vehicle repair. It is also how the value your car permanently lost gets left on the table, since diminished value is a separate recovery from repair cost.
Is the Number They Quoted the Number You Keep?
Almost never, and this is the single most overlooked part of an early offer. A provider lien recorded under A.R.S. § 33-931, along with any health plan’s reimbursement right, is satisfied out of your recovery rather than by the insurer.
Run it through: a $20,000 offer against $12,000 in billed treatment and a health plan asserting reimbursement can net a few thousand dollars once those obligations are met. The gross figure and the net figure are different numbers, and an adjuster quoting the gross is not being deceptive; they are simply not the one paying the liens.
Negotiating those claims down is part of building a case. It cannot happen after you have signed and disbursed.
Has a Fault Discount Already Been Applied?
Usually yes, and nobody tells you the percentage. Arizona applies pure comparative negligence under A.R.S. § 12-2505, reducing an award by the claimant’s share of fault with no cutoff. An early offer often has a fault reduction baked in 20%, 30% that you never agreed to and were never shown.
That figure is a negotiating position, not a finding. Neither an adjuster’s opinion nor the narrative section of a crash report fixes it, and how fault gets divided is contestable with reconstruction, scene evidence, and vehicle data.
One related point: if either driver paid a traffic citation, that does not settle liability. Under A.R.S. § 28-1599, an admission of a civil traffic complaint or a judgment on it is not evidence of negligence in a civil proceeding in either direction.
Is the Offer Actually the Policy Limit?
Sometimes it is, and that changes the analysis rather than ending it. A.R.S. § 28-4009 sets Arizona’s minimum liability limits at $25,000 per person and $50,000 per accident. If the adjuster has tendered the full limit, no amount of negotiating produces more from that policy.
The question then becomes whether other coverage exists: your own underinsured motorist coverage for the gap, uninsured motorist coverage if the driver had none or fled, a commercial policy behind a work or delivery vehicle, tiered rideshare coverage, or a dram shop claim against a licensee.
This is where a limited offer becomes dangerous rather than generous. Accepting and signing a general release before those layers are identified can compromise them. And in a multi-vehicle crash it matters even more, because A.R.S. § 12-2506 abolished joint and several liability each defendant owes only its own percentage, so releasing one does not shift that share onto the others.
Does Arizona Regulate How Insurers Handle This?
Yes. A.R.S. § 20-461, Arizona’s unfair claim settlement practices statute, prohibits conduct including misrepresenting pertinent facts or policy provisions, failing to act reasonably promptly on communications about a claim, and failing to attempt in good faith to effectuate prompt, fair and equitable settlement of claims in which liability has become reasonably clear.
Knowing the standard exists changes how you document the exchange dates, who said what, what was offered and on what basis. Where the claim is against your own carrier, such as an uninsured motorist claim, Arizona also recognizes a first-party bad faith claim for unreasonable denial or delay, which is worth understanding if the carrier refuses to pay.
When Does Accepting the First Offer Make Sense?
Sometimes it genuinely does, and it is worth saying plainly:
- Treatment is complete and your doctor has released you with no expected future care
- Liability is undisputed and no fault discount has been applied
- The injuries were minor, resolved quickly, and the offer covers the billed treatment plus a reasonable amount for what you went through
- The offer is the full policy limit and you have confirmed no other coverage layer applies
- No liens or reimbursement rights will consume the payment
If those are all true, taking it and moving on can be the right call. If any one of them is uncertain, rejecting the offer costs you nothing but time and negotiations do not pause the two-year filing deadline under A.R.S. § 12-542, so time is the resource to watch.
Frequently Asked Questions
Can I reopen a claim after I’ve signed a settlement release? Generally no. A release is a contract, and once it is signed and the payment accepted, the claim is closed even if your condition worsens or you need surgery later. That permanence is why the timing of the offer matters more than its size.
How long do I have to decide on a settlement offer? An offer usually has its own expiry, but the deadline that actually matters is the statute of limitations generally two years from the date of injury under A.R.S. § 12-542. Negotiating with an insurer does not pause it, and no carrier has a duty to warn you it is running out.
Will my settlement be reduced because I was partly at fault? Yes, by your assigned percentage but nothing bars recovery outright. Arizona is a pure comparative negligence state under A.R.S. § 12-2505, so a claimant found even 70% responsible may still recover 30% of proven damages. Early offers frequently have a fault discount built in that was never explained.
Why is the settlement so much less than my medical bills? Two reductions usually explain it: a comparative fault percentage, and a valuation of injuries made before treatment concluded. A third factor is that liens and health plan reimbursement come out of the gross figure, so the amount you keep is lower again.
Is it safe to cash the property damage check? Be careful with any check endorsed “final settlement” or “payment in full,” which can be argued to release more than vehicle repair. Property damage and injury claims are usually resolved separately, and repair cost does not include the market value a repaired vehicle permanently loses.
What if the offer is the full policy limit? Then more cannot come from that policy but other coverage may exist, including your own underinsured motorist coverage, a commercial policy, or rideshare coverage. Those layers should be identified before signing, because a general release can compromise them.
Before You Sign Anything
An offer made before your treatment concludes is a prediction about your recovery, made by the party paying for it. The only way to know whether it is a fair prediction is to compare it against complete medical records, a documented wage loss, and every coverage layer available.
Before you sign anything, a quick conversation with a Phoenix auto accident attorney can reveal whether that offer covers your true losses.
Harris Injury Law, PLLC 1136 E Campbell Ave, Phoenix, AZ 85014 (480) 800-4878
Consultations are free and cases run on a contingency fee, meaning no attorney fee unless compensation is recovered. Request a consultation or meet our attorneys. Every case depends on its own facts; no outcome can be promised or predicted.
This article provides general information about Arizona law and is not legal advice. Reading it creates no attorney-client relationship. Arizona law changes, and outcomes depend on the specific facts of a claim. Consult a licensed Arizona attorney about your situation.
Reviewed by Jason A. Harris, Harris Injury Law, PLLC.